Introduction
A strong investment portfolio is not simply a collection of investments that have performed well.
A strong portfolio starts with a clear purpose, an appropriate asset allocation, sensible diversification, and a process for monitoring and maintaining the investments over time.
The goal is not to predict which stock, fund, or market will perform best next. It is to build a portfolio that is aligned with your financial goals, time horizon, risk tolerance, and overall financial situation.
A portfolio can become weaker even when its individual investments appear reasonable. Concentration in one company or sector, overlapping funds, excessive fees, poor liquidity, or an asset allocation that no longer matches your goals can all create problems.
Building the portfolio is only the beginning. Investors also need a practical way to contribute money, review their holdings, manage costs, rebalance when appropriate, and respond to major changes in their financial circumstances.
In this guide, you’ll learn:
- What makes an investment portfolio strong
- How to start with a clear portfolio strategy
- How diversification fits into portfolio construction
- How to choose investments that match your strategy
- Why the number of holdings does not determine diversification
- How automation can support consistent investing
- What to monitor after building a portfolio
- How rebalancing can maintain your intended allocation
- Why investment costs matter
- When major life changes may justify reviewing your portfolio
- Common portfolio-management mistakes
- How investor behavior can affect long-term decisions
The goal is not to create a complicated portfolio.
The goal is to build a portfolio that is understandable, appropriately diversified, and manageable over time
Related: [The Power of Diversification: How Smart Investors Reduce Risk]
Related: [Mastering Risk in Investments – How to Guide for Beginners]
What Makes a Strong Investment Portfolio?
A strong investment portfolio is built around a clear strategy rather than a collection of investments chosen individually.
Several elements work together:
1. A Clear Financial Purpose
Every portfolio should have a reason for existing.
Your objective might be retirement, a home purchase, children’s education, or another long-term financial goal. The purpose of the money helps determine how much investment risk and market volatility may be appropriate.
Money that may be needed soon generally requires different treatment from money intended for a long-term goal.
2. An Appropriate Asset Allocation
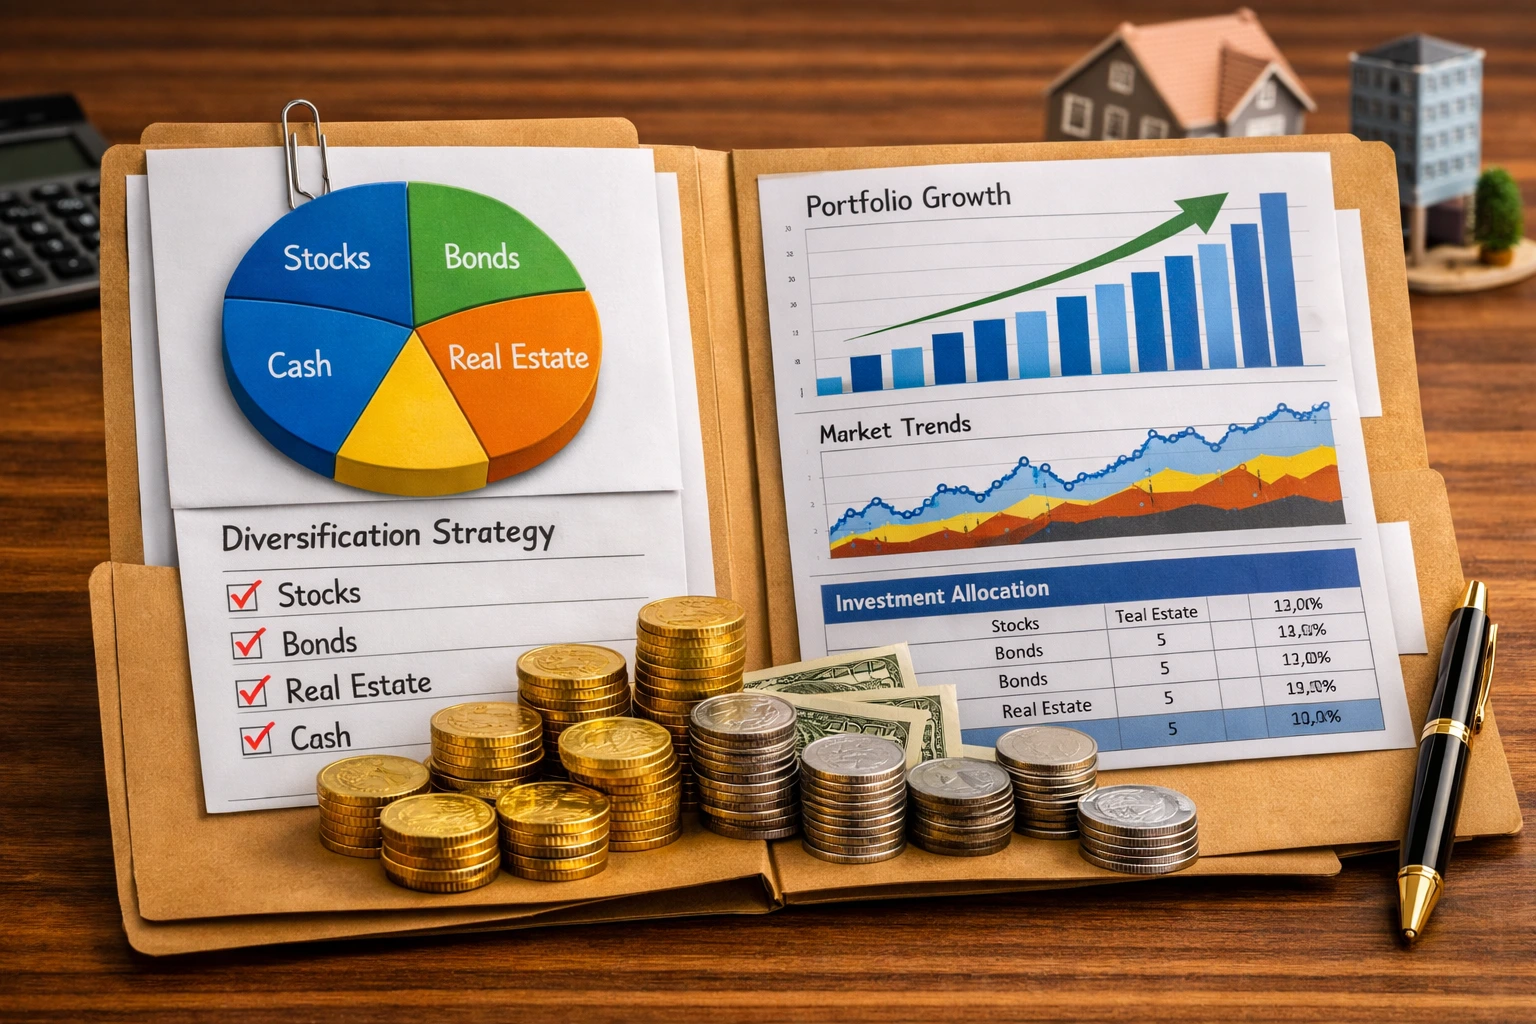
Asset allocation refers to how a portfolio is divided among major asset categories such as stocks, bonds, cash, and potentially other investments.
The appropriate mix depends on factors such as:
- Financial goals
- Investment time horizon
- Risk tolerance
- Ability to withstand losses
- Liquidity needs
- Overall financial situation
There is no single asset allocation that is appropriate for every investor.
3. Diversification
Diversification can reduce the impact of poor performance from any single investment, company, sector, or market.
However, diversification does not eliminate investment risk, and owning many investments does not automatically mean a portfolio is well diversified.
For a deeper explanation, see our guide on The Power of Diversification: How to Reduce Risk Smarter.
4. Investments That Match the Strategy
Individual stocks, bonds, mutual funds, ETFs, and other investments should have a clear role within the overall portfolio.
Instead of selecting an investment simply because it has performed well recently, consider whether it fits the portfolio’s intended asset allocation, risk level, diversification, and time horizon.
5. A Manageable Investment Process
A strong portfolio should also be practical to maintain.
Regular contributions, periodic reviews, appropriate rebalancing, and attention to investment costs can help keep the portfolio aligned with its original strategy.
The objective is not to monitor the market every day. It is to have a repeatable process that helps you stay aligned with your financial plan.
Step 1: Start With a Portfolio Strategy
Before choosing individual stocks, bonds, mutual funds, or ETFs, establish a clear strategy for the portfolio.
A portfolio strategy provides a framework for deciding how your money should be invested and how the portfolio should be managed over time.
Define Your Financial Goal
Start by identifying what the portfolio is intended to accomplish.
Your goal could include:
- Retirement
- Buying a home
- Children’s education
- Building long-term wealth
- Funding another major future expense
The purpose of the money can influence how much investment risk and market volatility may be appropriate.
Determine Your Investment Time Horizon
Your time horizon is the approximate period before you expect to need the money.
Money intended for a goal several decades away may have more time to withstand market fluctuations than money that will be needed within a few years.
As the time horizon becomes shorter, the potential impact of a market decline becomes more important to consider.
Consider Risk Tolerance and Risk Capacity
Risk tolerance is your willingness to remain invested when markets decline.
Risk capacity is different. It refers to how much financial loss you can realistically withstand without putting important financial goals at risk.
Both factors matter when developing a portfolio strategy.
An investor may be comfortable with market volatility but still have limited capacity for losses if the money will be needed soon.
Establish an Asset Allocation
Asset allocation refers to how a portfolio is divided among major asset categories such as stocks, bonds, and cash.
The appropriate allocation depends on factors such as:
- Financial goals
- Time horizon
- Risk tolerance
- Risk capacity
- Liquidity needs
- Overall financial situation
There is no single asset allocation that is appropriate for every investor.
For a broader explanation of how asset allocation works, see our guide on Asset Allocation Explained: The Secret to Long-Term Investing.
Write Down Your Strategy
A simple written strategy can make portfolio management easier.
You can document:
- The purpose of the portfolio
- Your expected time horizon
- Your intended asset allocation
- The types of investments you plan to use
- How you plan to make contributions
- How you will review the portfolio
- The circumstances that may lead to rebalancing
This creates a reference point for future decisions.
When markets become volatile, having a defined strategy can also help you avoid making decisions based solely on short-term market movements.
Once the strategy is established, diversification can help reduce unnecessary concentration within the portfolio.
Step 2: Diversify Without Overcomplicating Your Portfolio
Diversification is an important part of portfolio construction, but diversification does not mean buying as many investments as possible.
A portfolio can become concentrated if a large portion of its value depends on one company, sector, asset class, or geographic market.
You can reduce unnecessary concentration by considering diversification across areas such as:
- Companies or securities
- Industries and sectors
- Asset classes
- Geographic markets
Avoid Unnecessary Concentration
For example, owning several technology stocks does not necessarily create broad diversification if most of the portfolio still depends on the same sector.
Similarly, owning several funds does not automatically mean the portfolio is diversified. Different funds may hold many of the same companies.
Reviewing the underlying holdings can help identify this type of overlap.
Diversification Does Not Mean Eliminating Risk
Diversification can reduce the impact of poor performance from a particular investment or segment of the market, but it cannot eliminate investment risk.
A diversified portfolio can still decline when broad markets fall.
The purpose is to avoid having the outcome of the entire portfolio depend too heavily on a small number of investments or market segments.
For a detailed explanation of diversification, see The Power of Diversification: How to Reduce Risk Smarter.
For additional information about portfolio construction and diversification, see these resources from the U.S. Securities and Exchange Commission’s Investor.gov:
- Asset Allocation and Diversification — explains how asset allocation and diversification can be used when building an investment portfolio.
- Diversify Your Investments — explains the basic principles of diversification and spreading investment risk.
- Rebalancing — explains the process of bringing a portfolio back toward its intended asset allocation.
Step 3: Automate Contributions
Once you have a portfolio strategy, consistent contributions can make it easier to follow that strategy over time.
Automation does not determine which investments you should own. Instead, it can help you contribute according to a plan without relying on memory or short-term market sentiment.
Set a Sustainable Contribution Amount
Choose an amount that fits your income, expenses, emergency savings, debt obligations, and other financial priorities.
The amount does not need to be the same for every investor.
A contribution plan should be sustainable enough that you can continue it through different market conditions.
Use Automatic Transfers When Practical
You may be able to automate transfers from your bank account to an investment account according to a schedule.
For example, an investor might arrange for a portion of each paycheck to be transferred toward long-term investments.
The exact schedule matters less than having a process that is consistent with your financial plan.
Review the Plan as Your Finances Change
Automation should not mean ignoring your finances.
Review your contribution amount when there are significant changes in:
- Income
- Monthly expenses
- Debt
- Emergency savings
- Financial goals
- Investment time horizon
If your circumstances change, your contribution strategy may need to change as well.
The purpose of automation is to make a good financial process easier to follow—not to invest blindly without reviewing your overall plan.
Related: [Automated Savings – The Easy Way to Build Wealth Consistently]
Step 4: Choose Investments That Fit Your Strategy
After establishing your portfolio strategy, the next step is to select investments that fit the strategy.
An investment should not be added simply because it has recently performed well or is popular in the market.
Instead, consider how each investment fits into the portfolio as a whole.
Consider the Role of Each Investment
Before adding an investment, ask:
- What role does this investment play in the portfolio?
- Which asset class does it represent?
- Does it increase diversification or create additional concentration?
- How does it fit with the portfolio’s target allocation?
- What level of risk and volatility could it introduce?
- What costs are associated with owning it?
- How easily can it be bought or sold when needed?
These questions can help prevent a portfolio from becoming a collection of unrelated investments.
Individual Investments and Diversified Funds
Investors can build portfolios using individual securities, diversified mutual funds, ETFs, or a combination of approaches.
Broadly diversified funds can provide exposure to many securities through a single investment, while individual securities require the investor to manage concentration and diversification more directly.
Neither approach automatically creates an appropriate portfolio.
The important question is whether the investments collectively fit the strategy.
Avoid Choosing Investments Based Only on Recent Performance
An investment that performed strongly in the past may not produce the same results in the future.
Recent performance can be useful information to review, but it should not be the only factor used to decide whether an investment belongs in your portfolio.
A strong portfolio focuses on the relationship between the investment, the overall strategy, and the investor’s financial objectives.
Step 5: Look Beyond the Number of Holdings
A portfolio is not necessarily well diversified simply because it contains many investments.
The number of holdings is only one part of understanding diversification. What those investments actually own matters more.
Watch for Overlapping Investments
Two or more mutual funds or ETFs may appear different because they have different names or investment strategies, while still holding many of the same companies.
For example, an investor could own several funds that all have substantial exposure to the same large companies or sector.
This can create more concentration than the investor realizes.
Review the Underlying Holdings
When evaluating funds, consider reviewing information such as:
- Major holdings
- Sector exposure
- Geographic exposure
- Asset-class exposure
- Investment objective
- Expense ratio and other applicable costs
This can help you understand what you actually own across the portfolio.
Avoid Diversifying for the Sake of Diversifying
Adding more investments is not always beneficial.
A portfolio can become unnecessarily complicated when an investor keeps adding funds or securities without a clear reason.
A simpler portfolio can be easier to understand, monitor, and maintain when it provides appropriate diversification for the investor’s objectives.
The goal is not to maximize the number of holdings.
The goal is to understand the exposures within the portfolio and avoid unnecessary concentration.
Step 6: Monitor Your Portfolio
Building a portfolio is not a one-time task.
Once your investments are in place, periodic monitoring can help you determine whether the portfolio still matches your original strategy.
Monitoring does not mean checking your portfolio every day or reacting to every market movement.
Instead, focus on the factors that can materially affect your long-term plan.
Review Your Asset Allocation
Over time, different investments can grow or decline at different rates.
As a result, the portfolio’s actual allocation may gradually move away from the allocation you originally intended.
Reviewing the portfolio periodically can help you identify meaningful changes.
Review Investment Holdings
Check whether the investments still serve the purpose for which they were selected.
You may want to review:
- Changes in an investment’s objective
- Significant changes in its holdings
- Fees and expenses
- Changes in your overall asset allocation
- Unnecessary overlap between investments
- Whether the investment still fits your financial goals
Avoid Reacting to Every Market Movement
Markets can move significantly over short periods.
A strong portfolio-management process should distinguish between normal market fluctuations and changes that genuinely affect your long-term financial strategy.
Selling an investment simply because its price has fallen does not automatically make the portfolio safer.
Likewise, buying an investment solely because its price has recently risen can increase the risk of making decisions based on short-term market performance.
Establish a Review Routine
There is no requirement to monitor a portfolio every day.
A periodic review may be sufficient for many long-term investors, provided the portfolio is also reviewed when important financial or personal circumstances change.
The objective is to identify meaningful changes while avoiding unnecessary reactions to short-term market noise.
Step 7: Rebalance When Appropriate
Rebalancing means adjusting a portfolio when its actual asset allocation has moved away from the allocation established in the investment strategy.
For example, if a portfolio was originally designed with a particular mix of stocks and bonds, strong performance in stocks could eventually cause stocks to represent a larger percentage of the portfolio than intended.
Rebalancing can bring the portfolio closer to its target allocation.
Why Rebalancing Matters
Without periodic review, a portfolio’s risk characteristics can change as different investments perform differently.
Rebalancing can help maintain the asset allocation that was selected based on the investor’s goals, time horizon, and risk considerations.
However, rebalancing does not guarantee better investment returns or prevent losses.
When Should You Rebalance?
There is no single rebalancing schedule that is appropriate for every investor.
Some investors review their portfolio at regular intervals, while others use predetermined allocation ranges and rebalance when the portfolio moves sufficiently away from its target.
The important point is to establish a reasonable process rather than reacting to every short-term market movement.
Consider Taxes and Transaction Costs
Before rebalancing a taxable investment account, consider the potential tax consequences of selling investments.
Transaction costs may also matter depending on the investments and account involved.
In some situations, directing new contributions toward underweighted asset categories may help bring the portfolio closer to its target allocation without selling existing investments.
Rebalancing Should Follow the Strategy
Rebalancing works best when the target allocation was established for a clear reason.
The objective is not to constantly change investments in response to market performance.
Instead, rebalancing is a portfolio-management process designed to keep the portfolio aligned with its intended strategy.
For more detail on rebalancing, see the Investor.gov guide on Rebalancing.
Related: [Investment vs Savings – How to Grow Your Money Smarter]
Step 8: Review Fees and Investment Costs
Investment costs can affect the amount of money that remains invested for your long-term goals.
Even when an investment appears to perform well, fees and expenses can reduce the amount of the return that ultimately remains with the investor.
Types of Costs to Review
Depending on the investment and account, costs may include:
- Expense ratios for mutual funds and ETFs
- Trading commissions or transaction fees
- Account or advisory fees
- Sales loads or other fund-related charges
- Other applicable administrative expenses
Not every investment has all of these costs, and the structure varies by investment and account.
Compare Costs Before Investing
When comparing similar investments, review their costs alongside other factors such as investment objective, holdings, risk, and performance history.
A lower-cost investment is not automatically the right investment, but unnecessary costs can be an important factor when two investments provide similar exposure and serve the same purpose.
Look at Costs Across the Entire Portfolio
Reviewing one investment at a time may not reveal the total cost of managing the portfolio.
Consider the costs associated with the portfolio as a whole and whether each investment provides a useful role.
A strong portfolio is not necessarily the one with the lowest possible fees.
It is one where the costs are understood and reasonable for the investments and services being used.
Step 9: Review Your Portfolio After Major Life Changes
A portfolio that was appropriate in the past may no longer fit your circumstances after a significant financial or personal change.
Major changes can affect your financial goals, cash-flow needs, time horizon, or ability to tolerate investment losses.
Consider reviewing your portfolio after events such as:
- A significant change in income
- A major change in household expenses
- Marriage or divorce
- The birth or adoption of a child
- A major change in debt
- Buying or selling a home
- A change in retirement plans
- Approaching a major financial goal
- Receiving a substantial inheritance or other financial windfall
Reassess the Strategy, Not Just the Investments
When circumstances change, avoid immediately replacing individual investments.
First ask whether the underlying portfolio strategy still makes sense.
You may need to reconsider:
- Your financial goals
- Your investment time horizon
- Your liquidity requirements
- Your risk tolerance and risk capacity
- Your target asset allocation
- Your contribution level
- Your emergency savings
Only after reviewing these factors should you determine whether changes to the portfolio itself are appropriate.
Keep the Portfolio Connected to Your Financial Plan
Investments should support your broader financial objectives.
A portfolio review is therefore not simply a check of whether individual holdings are making money. It is an opportunity to determine whether the portfolio is still aligned with what you are trying to accomplish with your money.
A Hypothetical Portfolio Management Example
Consider a hypothetical investor who has built a diversified portfolio for a long-term financial goal.
The investor has established a target asset allocation and selected investments that fit that strategy. Over time, the portfolio changes as different asset categories perform differently.
Instead of making changes whenever the market moves, the investor periodically reviews the portfolio and asks:
- Has the asset allocation moved materially away from the intended strategy?
- Are any investments creating unnecessary concentration?
- Do the investments still serve their original purpose?
- Have fees or expenses changed?
- Have the investor’s financial goals or time horizon changed?
- Has the investor’s ability to tolerate investment losses changed?
Suppose the investor discovers that one part of the portfolio has grown substantially and now represents a larger allocation than originally intended.
The investor could review whether rebalancing is appropriate rather than automatically selling or buying investments based solely on recent market performance.
If the investor’s financial circumstances have also changed, the appropriate response may be to review the overall strategy before making portfolio changes.
This example illustrates an important principle: portfolio management is an ongoing process of reviewing the strategy, understanding the investments, and making changes when there is a clear reason to do so.
It is not about constantly trying to predict which investment will perform best next.
Frequently Asked Questions
What makes a strong investment portfolio?
A strong portfolio has a clear purpose, an appropriate asset allocation, suitable diversification, manageable costs, and a process for ongoing review and maintenance.
The appropriate structure depends on the investor’s goals, time horizon, risk tolerance, risk capacity, and liquidity needs.
How many investments should a portfolio have?
There is no universal number of investments that makes a portfolio strong or diversified.
A portfolio with many holdings can still be concentrated if those holdings have substantial overlap or exposure to the same companies, sectors, or markets.
The underlying exposures are more important than simply counting the number of investments.
Are mutual funds and ETFs automatically diversified?
Not necessarily.
Many mutual funds and ETFs hold a large number of securities, but some funds may be narrowly focused on a particular sector, industry, country, or investment theme.
Review the fund’s investment objective and holdings to understand the exposure it provides.
How often should I review my investment portfolio?
There is no single review frequency that applies to every investor.
A periodic review can help identify changes in asset allocation, investment costs, portfolio concentration, or personal circumstances.
A portfolio should also be reviewed when significant financial or life changes occur.
Should I rebalance my portfolio every year?
Not necessarily.
Rebalancing decisions can depend on the portfolio’s strategy, target allocation, the size of allocation changes, taxes, transaction costs, and the investor’s circumstances.
The important point is to have a defined process rather than automatically making changes based on short-term market movements.
Is a diversified portfolio guaranteed to make money?
No.
Diversification can reduce concentration risk, but it cannot eliminate investment risk.
A diversified portfolio can still lose value, including during periods when broad financial markets decline.
Should I choose investments based on their past returns?
Past performance should not be the only factor used to select an investment.
Consider the investment’s purpose, risk, costs, holdings, diversification, and fit within your overall portfolio strategy.
An investment that performed well in the past may not produce the same results in the future.
Can I build a strong portfolio with a small amount of money?
Yes. A portfolio can be developed gradually as an investor’s available capital increases.
The important considerations are having a clear strategy, using appropriate investments, managing costs, and maintaining a consistent process that fits the investor’s circumstances.
Common Portfolio Management Mistakes
Even a portfolio with good investments can become difficult to manage if the underlying process is weak.
Here are some common mistakes to avoid.
1. Choosing Investments Without a Clear Strategy
Adding investments simply because they are popular or have recently performed well can result in a portfolio with no clear purpose.
Start with the overall strategy and then choose investments that fit it.
2. Assuming More Holdings Always Mean More Diversification
Owning many funds or securities does not automatically create diversification.
Review the underlying holdings and look for unnecessary overlap or concentration.
3. Ignoring Investment Costs
Small recurring costs can affect long-term investment results.
Review expense ratios, account fees, transaction costs, and other applicable charges before and after investing.
4. Reacting to Short-Term Market Movements
Selling during a market decline or buying after a sharp rise can cause investors to make decisions that are inconsistent with their long-term strategy.
Short-term market movements do not necessarily mean that the underlying financial plan needs to change.
5. Rebalancing Without Considering Taxes and Costs
Rebalancing can help maintain a target allocation, but selling investments may create tax consequences in taxable accounts and may involve transaction costs.
Consider these factors before making changes.
6. Failing to Review Major Life Changes
A portfolio that was appropriate several years ago may no longer fit after a major change in income, expenses, debt, family circumstances, or financial goals.
Portfolio management should account for changes in the investor’s overall financial situation.
7. Making the Portfolio Too Complicated
Adding more investments, strategies, or accounts does not necessarily improve a portfolio.
A portfolio that is difficult to understand can also be difficult to monitor and maintain.
Aim for a structure that provides appropriate diversification while remaining understandable and manageable.
8. Treating Past Performance as a Guarantee
Strong historical performance does not guarantee future results.
Investment decisions should consider the investment’s role, risk, costs, diversification, and suitability within the overall portfolio rather than relying only on historical returns.
The Behavioral Side of Portfolio Management
Investment decisions are not based on numbers alone.
Market volatility can create fear, excitement, or pressure to make quick decisions. These reactions can sometimes lead investors away from their long-term strategy.
Avoid Making Decisions Based Only on Market Headlines
Financial markets are constantly affected by news, economic data, company announcements, and investor expectations.
Not every market movement requires a change to a long-term portfolio.
Before making a change, consider whether the underlying reason for the portfolio strategy has actually changed.
Create Rules Before You Need Them
A written investment strategy can make decisions easier during periods of market volatility.
For example, an investor can establish in advance:
- The purpose of the portfolio
- The target asset allocation
- The approach to diversification
- How contributions will be made
- How portfolio reviews will be conducted
- The circumstances that may lead to rebalancing
Having these decisions documented can reduce the temptation to make impulsive changes.
Focus on the Process
No portfolio can eliminate uncertainty or guarantee positive returns.
A disciplined process focuses on decisions that can be controlled, such as saving consistently, managing investment costs, maintaining appropriate diversification, reviewing the portfolio, and keeping the strategy aligned with financial goals.
The objective is not to predict every market movement.
It is to have a process that can be followed through different market conditions.
Conclusion
A strong investment portfolio is built through a clear strategy and consistent management rather than by trying to find the perfect investment.
Start by defining your financial goals, time horizon, risk considerations, and intended asset allocation. Then choose investments that fit that strategy and provide an appropriate level of diversification.
After the portfolio is established, continue to monitor its allocation, holdings, costs, and overall suitability. Rebalancing may be appropriate when the portfolio moves materially away from its intended allocation, while major financial or personal changes may require a broader review of the strategy.
There is no portfolio that eliminates investment risk or guarantees a particular return.
The objective is to build a portfolio that is appropriate for your circumstances, understandable enough to manage, and flexible enough to be reviewed as your financial situation changes.
A strong portfolio is not defined by how complicated it is.
It is defined by how well its investments work together to support your financial goals.
Disclaimer
This article is for educational and informational purposes only and is not financial, investment, tax, or legal advice.
Investment values can rise or fall, and past performance does not guarantee future results. Diversification can help manage concentration risk but cannot eliminate investment risk.
Consider your individual financial circumstances, goals, and risk factors before making investment decisions. Consult a qualified financial, tax, or legal professional when appropriate.